Published 23 October 2026 · Institutional sources checked 23 October 2026
Europe's payment debate often puts the digital euro, euro stablecoins and SEPA in the same sentence. They address overlapping problems but are not the same thing. A useful comparison starts by asking what the customer holds, who owes the customer, how a payment moves and what happens when it goes wrong.
What the ECB is testing
The European Central Bank has selected 36 payment service providers for a pilot due to begin in the second half of 2027 and run for 12 months. Selected central-bank staff and merchants would test a beta digital euro in everyday transactions. The beta will not have legal-tender status. A final decision to issue a digital euro comes only after legislation is adopted. The ECB says it aims to be ready for a possible first issuance in 2029 if the legislative process proceeds as expected; that is an aim, not a launch date. ECB pilot announcement ↗ ECB pilot page ↗
Where a stablecoin differs
A euro-referenced stablecoin is a private issuer's promise or arrangement designed to track the euro. It is not central-bank money. Its usefulness depends on the issuer's rules, reserves, redemption process, intermediaries and the law that applies to the specific token. The EU's MiCA framework regulates certain crypto assets and service providers, but European supervisors warn that protection can still be limited. ESMA advises users to check the exact authorised legal entity, not just a familiar brand. Joint consumer warning ↗ ESMA authorisation statement ↗
SEPA is neither of those
SEPA is a set of schemes for euro payments through participating providers. Serbia's 18 participating banks illustrate a different route to improvement: making transfers work more smoothly without creating a new currency or token. The Commission expects lower costs and faster transfers, but its estimated savings are potential, not yet observed. Commission on Serbia joining SEPA schemes ↗
What blockchain could reveal about public money
There is a serious case for the technology beyond speculation. On a public blockchain, transfers between addresses leave a durable, inspectable record. If a public agency identifies its payment addresses and links each transfer to a published contract, invoice and recipient, auditors and citizens could compare what was authorised with what was actually sent. That could make unexplained diversions easier to spot. The World Bank is testing a related idea through FundsChain ↗, which tracks project commitments, payments and supporting documents across participating organisations. Its system is shared with project stakeholders; it is not an open public-chain record of every government expense.
Imagine a school repair budget: the published contract names the contractor, a verified address receives a payment, and completion documents are connected to that payment. The visible trail would give journalists and residents better questions to ask about cost and delivery. That is a possible design, not a claim that France or Serbia currently runs its budgets this way. A useful test would compare the published payments with the physical work and independent audit findings.
Where the trail still ends
A transaction record shows addresses, amounts and times; it does not automatically identify the people behind the addresses or prove that a school was repaired. Money may move through bank accounts, cash or an exchange's internal ledger without appearing on a public chain. The FATF's 2026 report ↗ explains why pseudonymous records need reliable identity information and why some transfers happen off-chain. Publication also has to protect legitimate private details. The most valuable reform may therefore combine traceable payments with open procurement, verified ownership, sound records and auditors who can act on what they find.
The real comparison
For a shopper or small exporter, a payment has several costs: the quoted fee, exchange rate, settlement time, rejected payments and the effort needed to resolve a dispute. A digital euro might change the nature of the payment claim; a stablecoin might offer a different technical route; SEPA improves a network already used by banks. No one metric settles which is best. The answer varies by use case and by the legal rights attached to it.
Editorial reflection
Better payments and better accountability can reinforce each other. A ledger that lets people follow public funds from an approved budget to a verified recipient could make secrecy harder and trust easier to earn. The test is whether the records connect to real contracts, real work and independent scrutiny. For everyday payments, measure fees, speed, legal rights and privacy as carefully as the technology itself.
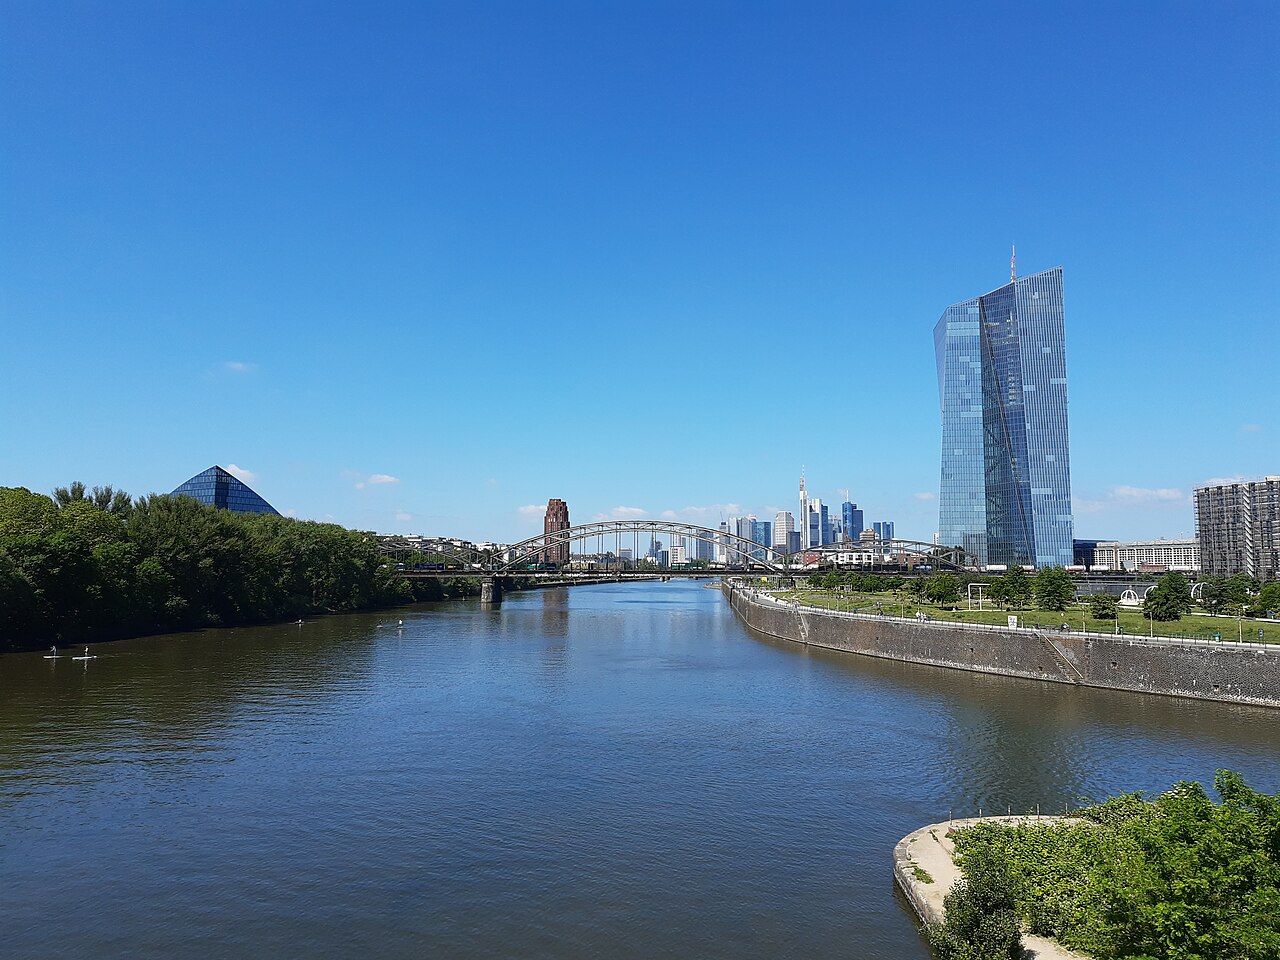
The opening photograph of the ECB and Frankfurt skyline dates to 2021. It illustrates the institution, not the 2027 pilot. No investment recommendation is made.